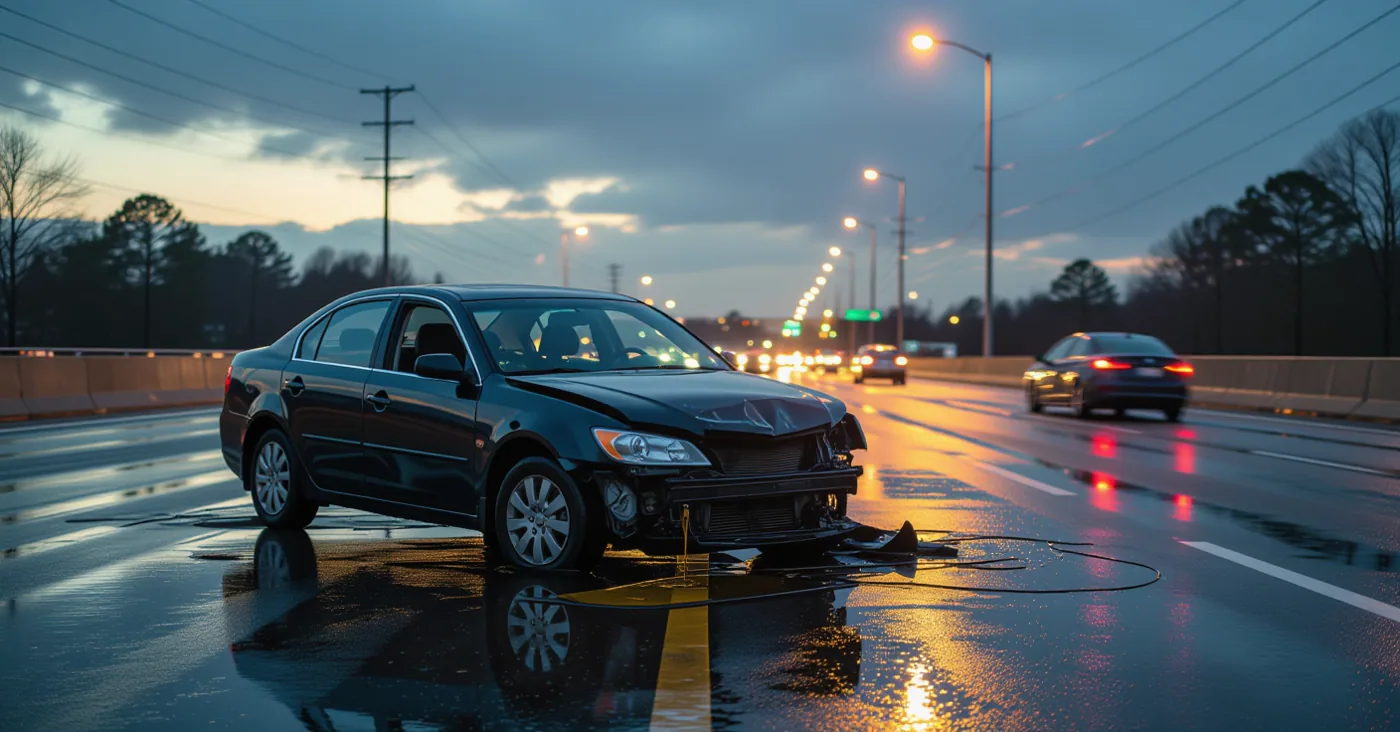
Immediate Steps After a Collision in the Upstate
If you have been involved in a motor vehicle accident on I-85, I-385, or a local Greenville road, your immediate priority is safety and documentation. However, one of the most critical administrative tasks often overlooked in the adrenaline of the moment is notifying your insurance provider. In South Carolina, the obligation to report an accident is not merely a courtesy; it is a contractual requirement that can dictate whether you have coverage when it matters most.
Many drivers hesitate to call their insurer, fearing rate hikes or policy cancellation. While these are valid concerns, silence is often riskier than notification. South Carolina law and standard auto insurance policies generally require prompt reporting of any accident involving injury, death, or property damage exceeding a certain threshold. Failing to report can be grounds for your insurer to deny your claim entirely, leaving you personally liable for damages that could easily total tens of thousands of dollars.
Understanding South Carolina’s Fault System
South Carolina operates under a "modified comparative negligence" rule. This means that if you are partially at fault for an accident, your compensation may be reduced by your percentage of fault. However, if you are found to be 51% or more at fault, you are barred from recovering any damages from other parties.
This system makes accurate reporting even more vital. Your insurance company will investigate the scene, review police reports from the Greenville County Sheriff’s Office or local police departments, and assess liability. If you delay reporting, your insurer may lack the evidence needed to establish that another driver was fully at fault. Without a timely report, the narrative of the accident can become murky, potentially shifting the blame onto you and jeopardizing your ability to seek recovery for medical bills or vehicle repairs.
The 3-Year Statute of Limitations
In South Carolina, you generally have three years from the date of the accident to file a personal injury lawsuit. This is known as the statute of limitations. While this timeline applies to legal action, it underscores the importance of acting quickly. Insurance claims often require extensive documentation, including medical records, repair estimates, and witness statements.
If you wait too long to report the accident, you may find yourself scrambling to gather evidence that has since disappeared. Skid marks fade, surveillance footage is overwritten, and witnesses’ memories diminish. By reporting the accident immediately, you initiate the formal process that preserves your rights. Even if you do not plan to sue, your insurer needs the case number and initial details to open a file and begin their investigation within this critical window.
When Is Reporting Mandatory?
While you should always report accidents to be safe, South Carolina law specifically mandates reporting to the Department of Motor Vehicles (DMV) if the accident results in injury, death, or property damage exceeding $1,000. Most insurance policies mirror this requirement. If your damage exceeds your deductible or involves another vehicle, you must report it.
Consider these scenarios common in the Greenville area:
* Minor Fender Benders: If you hit a parked car or have a minor rear-end collision with no injuries, check your policy. Some policies allow you to handle minor repairs without a formal claim, but you still may need to notify them if there is any uncertainty about damage.
* Injuries: Any accident involving whiplash, fractures, or even minor cuts requires immediate reporting. Medical costs can escalate quickly, and your health insurance may seek reimbursement from the at-fault party’s insurer.
* Hit-and-Run: If you are hit by an uninsured driver who flees the scene, your own uninsured motorist coverage may apply. However, you must report the incident to your insurer and often to the police to trigger this coverage.
Impact on Your Premiums and Policy
Drivers often worry that reporting an accident will lead to an immediate spike in premiums. While this is possible, the impact depends on several factors, including your driving history, the severity of the accident, and whether you were at fault. In South Carolina, insurers are regulated, and rate increases are not automatic for every reported incident, especially if you are not at fault.
If you are not at fault, your insurer may seek subrogation, meaning they will recover costs from the at-fault party’s insurance company. In many cases, this can prevent your rates from increasing. Even if your rates do go up, the cost of a premium increase is often far less than the out-of-pocket expense of paying for repairs and medical bills yourself. Transparency with your insurer builds trust and ensures that your policy remains active and valid.
Document Everything for the Greenville Insurer
When you report your accident to your insurance company in South Carolina, provide as much detail as possible. Have the following information ready:
1. Police Report Number: Obtain this from the responding officer or the local police department.
2. Photos: Images of vehicle damage, license plates, and the accident scene.
3. Witness Information: Names and contact details of any bystanders.
4. Medical Records: If you sought treatment, keep copies of all bills and diagnoses.
Accurate and timely reporting helps your insurer process your claim efficiently. It also protects you if the other party later disputes liability. In the busy corridors of I-85 and I-385, where accidents are frequent, having a clear, documented record can make the difference between a smooth resolution and a protracted legal battle.
Take Control of Your Next Steps
Navigating the aftermath of a car accident in South Carolina requires careful attention to legal deadlines and insurance protocols. Reporting your accident promptly is not just a rule; it is a strategic move to protect your financial interests and ensure you receive the compensation you deserve.
If you are unsure about your obligations or need guidance on how to proceed, consult with a local personal injury attorney. A free case evaluation can help you understand your rights under South Carolina law and determine the best course of action for your specific situation.